Is HMRC quietly changing the way businesses pay their taxes?
Most Budget coverage concentrates on how much tax people will pay. Rates, thresholds, allowances and reliefs understandably attract attention because their financial consequences are relatively easy to identify. But the supporting documents to Budget 2026 contain several announcements concerned with something different: how tax liabilities are reported, how frequently they are paid and what happens when payment isn't made.
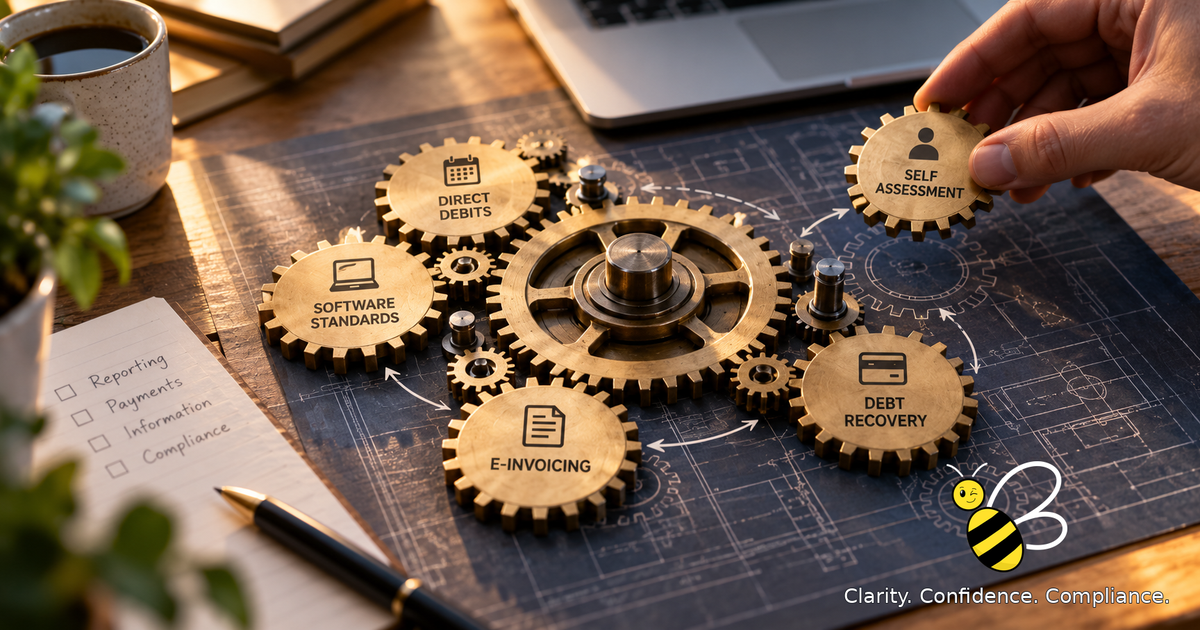
Individually, these measures look like administrative reforms. Taken together, they suggest that HMRC is moving towards a system in which more information is exchanged automatically, tax is collected more regularly and businesses have less need to initiate each stage of the process themselves.
There are good reasons for modernising tax administration, particularly if it reduces errors, prevents unexpected debts and makes compliance easier. The interesting question is whether those improvements will be accompanied by adequate safeguards when information is incorrect, liabilities are disputed or taxpayers face genuine financial difficulties.
The Direct Debit that businesses may not have expected
From April 2029, the government intends to require businesses to establish Direct Debit arrangements for VAT and PAYE return liabilities, subject to defined exceptions. Businesses will still be able to pay using other methods before the payment deadline, but HMRC will use the Direct Debit instruction to collect any balance remaining unpaid at that point.
This is not the same as requiring businesses to pay all their taxes exclusively by Direct Debit. Nevertheless, it changes the starting position by giving HMRC an established means of collecting an unpaid liability without waiting for the taxpayer to initiate a separate payment.
For businesses with predictable cash flow and reliable reporting, the change might make little practical difference. Others may need to think more carefully about how they manage their tax accounts, particularly where income is irregular or a return needs correcting. The operational safeguards will matter, including how much notice HMRC provides before collection and what happens when a liability is being challenged.
Self Assessment tax payments could become more frequent
Another proposal concerns individuals who already make Payments on Account through Income Tax Self Assessment. From April 2029, the government intends to introduce more frequent, automated payments during the tax year, with eligible taxpayers also able to choose collection through PAYE.
The potential benefit is straightforward. Smaller, regular payments could make tax easier to budget for, reducing the risk of a substantial liability arriving when the money is no longer available. For people whose income is relatively predictable, that could be a welcome improvement over the familiar January and July payment dates.
However, self-employed income is not always earned evenly throughout the year. Seasonal businesses, contractors and people whose earnings fluctuate may rely on cash reserves to cover quieter periods or unexpected expenditure. Under the proposed arrangements, payments will continue to be based on the previous year's tax liability, although taxpayers will be able to adjust the amounts online when their circumstances change.
The transition in 2029–30 also deserves attention. Taxpayers will need to finish paying their liability for the previous year while beginning the new, more frequent payments. The government has not yet determined how often those payments will be collected, and much will depend on the final arrangements for calculating and adjusting them.
Recovering tax debts directly from bank accounts
Perhaps the most striking announcement concerns the recovery of established tax debts. The government intends to introduce a power allowing HMRC to recover qualifying lower-value debts through regular deductions directly from bank accounts, aimed at taxpayers who are considered able to pay but repeatedly fail to engage with the department.
There is a reasonable argument for strengthening the recovery of debts from people who can afford to pay but deliberately avoid doing so. Unpaid tax affects public finances, while businesses that meet their obligations should not be disadvantaged by competitors who fail to meet theirs. The proposed power is intended for established lower-value debts where taxpayers have repeatedly failed to engage with HMRC, rather than as an alternative way of collecting ordinary VAT or PAYE liabilities.
The difficulty lies in establishing what someone can reasonably afford. A business may have money in its account that is already committed to wages, suppliers or other essential expenditure. Equally, a taxpayer who has failed to engage with HMRC may be experiencing financial difficulties rather than deliberately avoiding payment.
The government has responded to consultation concerns by proposing individual affordability assessments, a minimum 28-day notice period before deductions begin, protections for taxpayers requiring additional support and a mechanism for refunding disputed deductions while HMRC reviews an objection. These safeguards will be central to whether the new powers can distinguish effectively between taxpayers who will not pay and those who cannot.
Electronic invoicing and the information HMRC receives
Mandatory electronic VAT invoicing was first announced at Budget 2025, with implementation planned for April 2029. Budget 2026 takes that commitment forward by publishing an implementation roadmap and proposing the legislation needed to establish the new requirements. This involves more than replacing paper invoices with PDFs: the intention is to use structured electronic information that can be exchanged between accounting systems in a prescribed format, reducing manual entry and making transactions easier to reconcile.
There are obvious potential benefits for businesses, particularly those processing large volumes of invoices. Better-quality information could reduce errors, improve record keeping and simplify parts of the VAT process. It may also create opportunities for greater automation across accounting and tax administration.
However, mandatory electronic invoicing should not be confused with a requirement to transmit every invoice directly to HMRC. The government is separately considering how structured invoice information might be used in future tax reporting. Although the developments are related, they involve different obligations and should be assessed separately.
For businesses, implementation will raise practical questions about software compatibility, costs and the ability to exchange information with customers and suppliers using different systems. The benefits will depend on whether the new requirements genuinely simplify existing processes or merely replace them with different administrative obligations.
The growing importance of tax software
Alongside these changes, the government intends to strengthen the standards applying to software providers that integrate with HMRC systems. This may initially appear to be a matter for developers, but businesses increasingly depend on software to calculate liabilities, prepare returns, submit information and maintain compliance records.
Improving software quality and reliability is a worthwhile objective. As more of the tax system becomes automated, errors in software or the information supplied to it can have consequences that extend well beyond an incorrect calculation. A mistake may affect a submitted return, an expected payment or the information HMRC uses to assess compliance.
There are also potential costs to consider. More demanding standards could increase development and compliance expenditure, particularly for smaller providers, while businesses may become increasingly dependent on a limited number of software platforms.
The wider issue is one of responsibility. Automation can make a process faster and more consistent, but it does not remove the need for professional judgement or clear accountability. Businesses still need to understand what their systems are doing, how errors can be identified and who is responsible for resolving them.
Will tax administration become better for taxpayers?
There is a recognisable direction running through these announcements. HMRC wants more reliable information, more regular payment of liabilities and more effective recovery where tax remains unpaid. Those objectives are understandable, and a system that reduces errors, unexpected bills and unnecessary administration could benefit taxpayers as well as the department.
The difficulty is that efficiency can look different depending on whose perspective is being considered. More frequent payments may reduce outstanding tax debt while making cash-flow management harder for some businesses. Direct collection may improve compliance but increase the consequences of an incorrect liability. Structured digital reporting may simplify administration over time while requiring businesses to invest in new systems and processes.
None of these concerns necessarily outweighs the benefits. They do, however, suggest that the success of the reforms should be measured by more than how quickly information reaches HMRC or how efficiently tax is collected. Taxpayers also need to understand their liabilities, correct mistakes, challenge decisions and retain reasonable control over their finances.
The individual measures have different implementation dates, legislative requirements and safeguards. They should not be treated as one completed programme, nor as evidence that HMRC is about to gain unrestricted access to business bank accounts.
Nevertheless, considered together, they suggest a gradual change in the relationship between taxpayers and the tax authority. Reporting, calculating and collecting tax are becoming more closely connected, with technology increasingly involved at every stage.
That could represent a genuine improvement in tax administration, provided the systems are accurate, proportionate and designed around the circumstances of the people using them. The test will be whether modernisation makes compliance easier and fairer for taxpayers, rather than simply making collection more efficient for HMRC.
Ready To BeePayWise?
Let’s make your payroll the sweetest, calmest part of your month. Book a hive chat for a no-strings mini-diagnostic, or drop us a message and we’ll buzz right back.