Your payroll was right. Does that mean your payroll process is good?
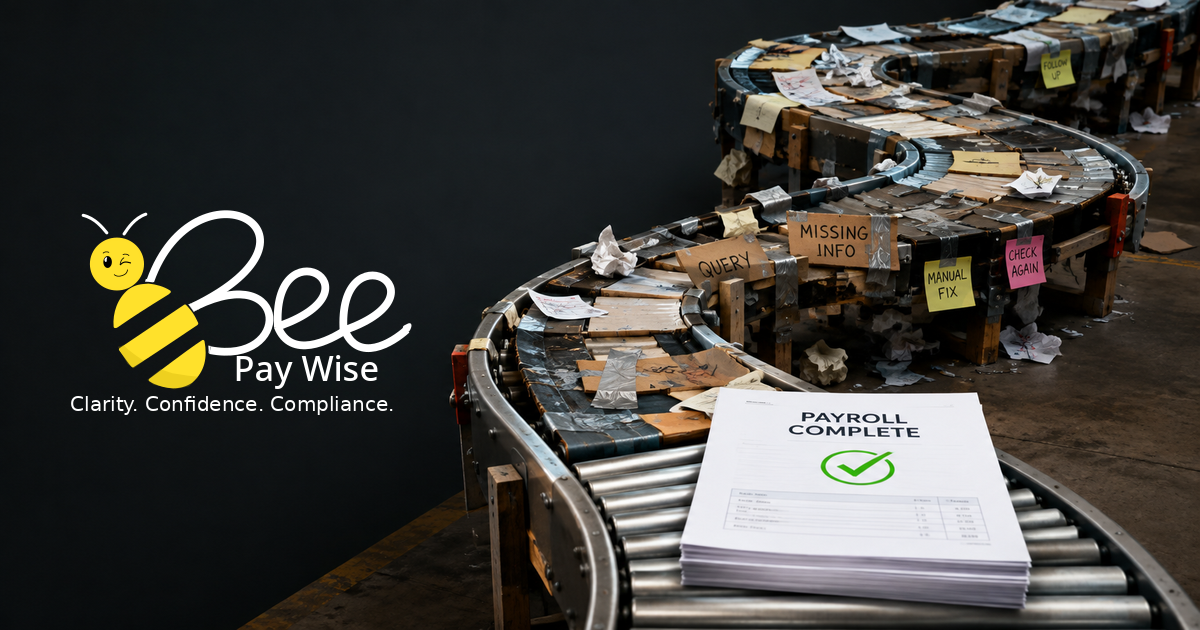
A payroll can be completely accurate and still tell you something important about the process behind it.
Imagine two organisations running payroll for the same number of employees.
In the first, the information arrives complete and on time. Changes are properly authorised, the payroll is processed, the expected checks are completed and everything is correct.
In the second, the information arrives late and contains several problems. An experienced payroller spots them, chases missing information, queries something that does not look right and makes a correction before the payroll is finalised.
That payroll is correct too.
If we judge the two processes only by their final output, they look identical. Everyone received the right pay.
But they did not take the same route to get there.
Accuracy tells you what happened, not how it happened
A correct payroll is obviously a good outcome. The problem comes when we treat that outcome as evidence that everything behind it must also be working well.
Sometimes accuracy is produced by a reliable process. Sometimes it is produced because somebody intervened when the process did not work as intended.
Those interventions are often exactly what good payroll professionals should be doing. They check, question and sense-check rather than blindly processing whatever reaches them.
But that creates an interesting problem.
The better somebody becomes at catching issues, the easier it can be for the underlying issues to disappear from view.
Look at what had to happen
One useful payroll control is a variance check: comparing the current payroll with an earlier period and investigating movements that look unusual.
Suppose an employee's pay changes significantly. The variance check identifies it, the payroller investigates and discovers that incorrect information was supplied. The problem is corrected before payment.
The control worked, but the fact that it worked does not make the original problem irrelevant.
If the same type of incorrect information repeatedly reaches payroll, the variance check may keep protecting the employee from the consequence. It does not necessarily address why the information keeps arriving incorrectly.
That distinction matters because otherwise successful intervention can look exactly like successful process.
What is the payroll result actually telling you?
The point is not to treat every query or correction as evidence of a broken process. Payroll contains exceptions, judgement and legitimate changes. Good controls exist partly because unusual things happen.
The useful question is whether those interventions are exceptional or whether they have quietly become necessary to produce the expected result.
If payroll is consistently correct because the same person remembers to chase the same missing information, correct the same recurring issue or apply the same workaround, the final accuracy figure may be hiding something worth understanding.
So alongside asking whether payroll was right, ask:
What had to happen to make it right?
If the answer is simply that the normal process and controls worked as intended, that is useful evidence of a reliable process.
If the answer reveals repeated intervention, correction or workaround, that is useful evidence too.
The payroll result has not become less successful, it has simply told you something more interesting than whether the numbers were right.
Ready To BeePayWise?
Let’s make your payroll the sweetest, calmest part of your month. Book a hive chat for a no-strings mini-diagnostic, or drop us a message and we’ll buzz right back.